I. The Statutory Framework
The Internal Revenue Code imposes a tax on “taxable income” of every individual. 26 U.S.C. § 1. Taxable income is computed from “gross income.” 26 U.S.C. § 63. And gross income is defined, at 26 U.S.C. § 61(a), in language whose breadth has been the subject of seventy years of litigation and not one square inch of ambiguity:
“Except as otherwise provided in this subtitle, gross income means all income from whatever source derived.”1
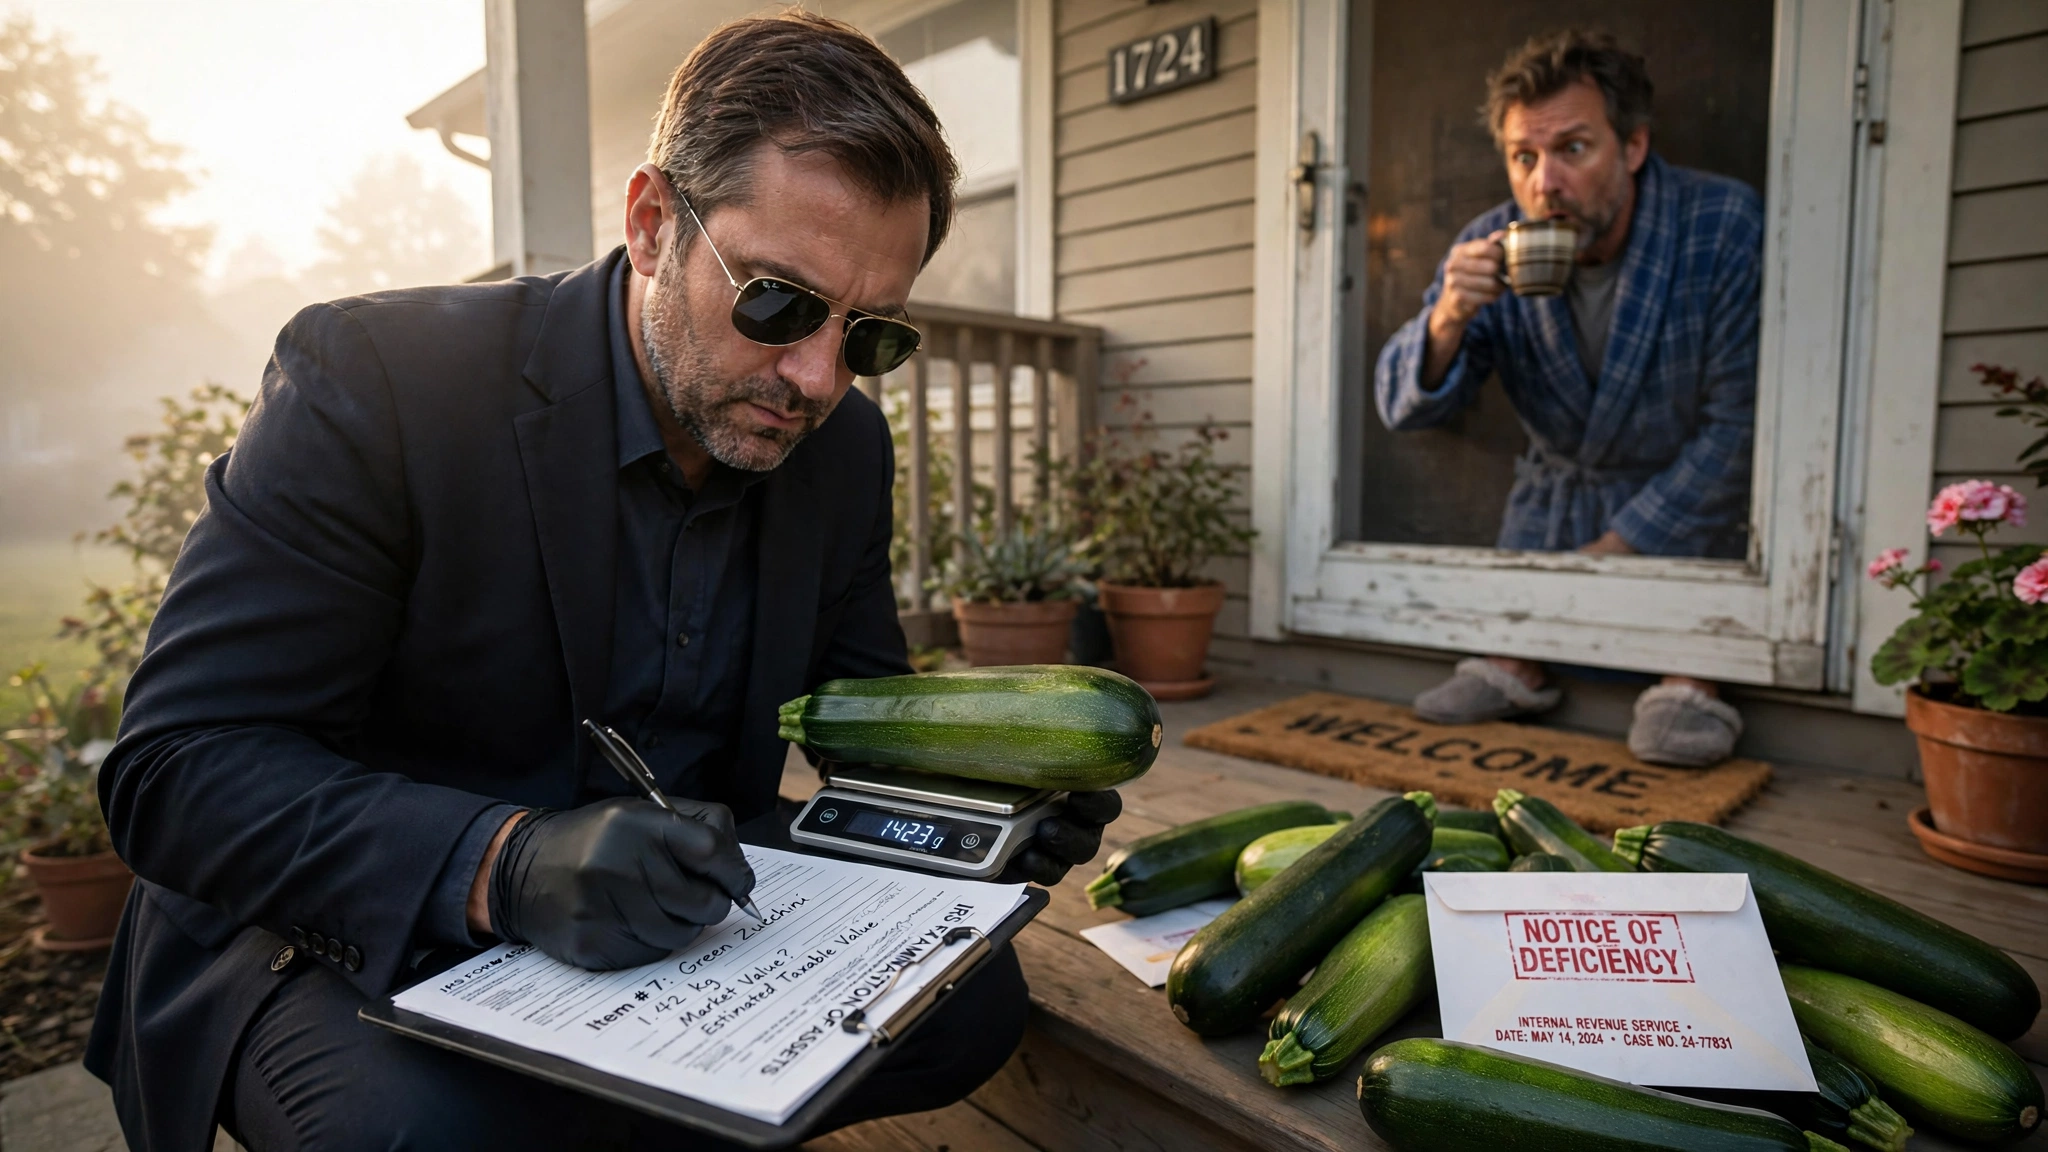
The statute then provides a non-exhaustive list of fifteen categories of income: compensation for services, gross income derived from business, gains from dealings in property, interest, rents, royalties, dividends, annuities, income from life insurance and endowment contracts, pensions, income from discharge of indebtedness, distributive share of partnership gross income, income in respect of a decedent, and income from an interest in an estate or trust. The fifteenth item is a catchall. But the catchall is unnecessary, because the predicate clause already captures everything. “All income from whatever source derived” does not leave gaps. It leaves a zucchini-shaped hole in the national tax base.
II. The Glenshaw Glass Test
In 1955, the Supreme Court confronted the question of whether punitive damages received in an antitrust lawsuit constituted gross income. The taxpayers argued that such damages were not “derived from capital, from labor, or from both combined”—the formulation the Court had used in Eisner v. Macomber, 252 U.S. 189 (1920). The Court rejected this argument and established the test that has governed gross income analysis for seven decades:
“Here we have instances of undeniable accessions to wealth, clearly realized, and over which the taxpayers have complete dominion.”2
Three prongs. Three questions. The test applies to every item of value that crosses the threshold of every American household.
Prong one: undeniable accession to wealth. A zucchini has a fair market value. The USDA Agricultural Marketing Service reports that fresh summer squash, of which zucchini is the predominant variety, retails at prices ranging from approximately $1.00 to $2.50 per pound, depending on the season, region, and whether the word “organic” appears on the label.3 A medium zucchini weighs approximately seven to eight ounces. The value of that zucchini, at prevailing retail prices, is approximately $0.50 to $1.25. This is not nothing. A zucchini has more fair market value than a penny, and the IRS has never suggested that pennies found on the ground are excludable from income.
Prong two: clearly realized. There is no ambiguity about whether the zucchini has been received. It is on the porch. It is green. It is approximately fourteen inches long. It was not there yesterday. It is, in the language of the regulation, “actually or constructively received.”4
Prong three: complete dominion. The recipient can eat the zucchini, sell the zucchini, give the zucchini to someone else, leave the zucchini on a third party’s porch, or throw the zucchini in the compost. The recipient exercises unfettered control over the disposition of the zucchini. The recipient has, in the language of the Supreme Court, “such control over it that, as a practical matter, he derives readily realizable economic value from it.”5 One does not need a brokerage account to realize the value of a zucchini. One needs a cutting board.
All three prongs are satisfied. The zucchini is gross income under Glenshaw Glass. The analysis is complete unless an exclusion applies.
III. The Gift Exclusion
Section 102(a) of the Internal Revenue Code provides: “Gross income does not include the value of property acquired by gift, bequest, devise, or inheritance.”6
This is the exclusion upon which the nation’s gardeners implicitly rely. They do not cite it. They have not read it. But the unstated assumption of every person who has ever left a bag of zucchini on a neighbor’s front step is that this is a gift, and gifts are not taxable.
The assumption requires examination.
IV. The Duberstein Problem
In Commissioner v. Duberstein, 363 U.S. 278 (1960), the Supreme Court confronted the question of what constitutes a “gift” within the meaning of § 102(a). Duberstein, the president of a metal company, had received a Cadillac from the president of a company with which he did business, purportedly as a “gift” in appreciation for business referrals. The Court held that the Cadillac was not a gift. It was income.7
The Court established that the statutory term “gift” does not carry its common-law meaning. A voluntary transfer without legal consideration is not automatically a gift for tax purposes. Instead, the Court held that “a gift in the statutory sense… proceeds from a ‘detached and disinterested generosity,’” quoting Commissioner v. LoBue, 351 U.S. 243, 246 (1956), and from “‘affection, respect, admiration, charity or like impulses,’” quoting Robertson v. United States, 343 U.S. 711, 714 (1952).8
Conversely, if the transfer proceeds primarily from “the constraining force of any moral or legal duty,” or from “the incentive of anticipated benefit” of an economic nature, it is not a gift. Bogardus v. Commissioner, 302 U.S. 34, 41 (1937).9
The “most critical consideration,” the Court held, “is the transferor’s ‘intention.’”10
And so the tax treatment of a zucchini turns on a single factual question: what is the transferor’s intention when leaving surplus produce on a neighbor’s porch?
V. The Transferor’s Intention
The question answers itself, and the answer is not generous.
The act of leaving surplus zucchini on a neighbor’s porch is so widely understood as a self-interested act of agricultural disposal that the United States has designated a national day for it. August 8 is “National Sneak Some Zucchini Onto Your Neighbor’s Porch Day,” created by Tom Roy of Wellcat Holidays as—in the creator’s own words—a way of “ridding yourself of unwanted surplus summer squash.”11
Consider the language. “Ridding yourself.” “Unwanted.” “Surplus.” This is not the vocabulary of detached and disinterested generosity. This is the vocabulary of waste management. The transferor is not giving. The transferor is disposing. The porch is not a gift table. It is a drop-off point.
The Old Farmer’s Almanac, which has published guidance on agricultural practices since 1792, instructs celebrants of the holiday to “simply wait until the dead of night and quietly creep up to your neighbors’ front doors.”12 Gifts are made openly. Gifts are accompanied by a card. Gifts are received with gratitude. No one creeps. The fact that the recommended delivery method is indistinguishable from the modus operandi of a residential burglary suggests that the transferor is aware, at some level, that the transfer is not welcome.
Under Duberstein, a transfer motivated by the transferor’s desire to rid themselves of unwanted property is not a gift. It is a deposit. And the recipient has income.
VI. The Cucurbit Economy
The scale of unreported zucchini income is not trivial.
The National Gardening Association’s Special Report, cited in publications from the National Garden Bureau and multiple university extension services, found that 35 percent of U.S. households—approximately 42 million households—grow food at home, including fruits, vegetables, berries, and herbs.13 Summer squash, the botanical category that includes zucchini, is grown by 32 percent of food gardeners, making it the sixth most popular homegrown vegetable in the United States after tomatoes (86%), cucumbers (47%), sweet peppers (46%), beans (39%), and carrots (34%).14
Thirty-two percent of 42 million is approximately 13.4 million households growing summer squash.
The University of Maryland Extension’s growing guide for summer squash documents an approximate yield of “20 to 40 lbs. per 10-foot row.”15 Individual plant yields range from 3 to 10 pounds over a growing season, with prolific varieties producing 2 to 3 harvestable fruits per plant per week during peak season.16 The plant is, by the standards of home gardening, an overachiever. It does not have an off switch. It does not respond to social cues. It continues to produce fruit long after the household has exhausted its interest in zucchini bread, zucchini fritters, zucchini noodles, and the quiet contemplation of what it means to have planted three more zucchini hills than a family of four can consume.
If each of the 13.4 million summer squash households produces a conservative average of 15 pounds of zucchini per season, and shares a conservative 20 percent of that surplus with neighbors—a figure that is, if anything, low, given that university extension services routinely advise home gardeners to “share with friends, neighbors, and food banks” as a strategy for surplus management17—the result is approximately 40.2 million pounds of zucchini transferred between households annually without a single income reporting event.
At an average retail value of $1.50 per pound, the fair market value of unreported zucchini transfers in the United States is approximately $60.3 million per year.
VII. The Fair Market Value Calculation
Treasury Regulation § 1.61-2(d)(1) provides that “[i]f services are paid for in property, the fair market value of the property taken in payment must be included in income.”18 The regulation applies with equal force to property received in exchange for no services at all, because the broader statutory framework at § 61(a) does not require an exchange. It requires only income “from whatever source derived.”
The IRS has provided extensive guidance on the valuation of non-cash income. Revenue Ruling 79-24 established that when a taxpayer receives property or services in exchange for services, the fair market value of the property or services received must be included in gross income.19 The ruling addressed a house painter who painted a lawyer’s house in exchange for legal services. Both the fair market value of the painting and the fair market value of the legal services were includable in the respective taxpayers’ gross incomes. The IRS has maintained this position without interruption for forty-seven years.
The fair market value of a zucchini is not difficult to determine. It is the price at which a zucchini would change hands between a willing buyer and a willing seller, neither being under any compulsion to buy or sell, and both having reasonable knowledge of relevant facts. Treas. Reg. § 20.2031-1(b).20 Grocery stores sell zucchini. Farmers’ markets sell zucchini. The USDA Agricultural Marketing Service publishes terminal market prices for summer squash. There is no valuation ambiguity. There is only a filing omission.
VIII. The Information Reporting Gap
Under 26 U.S.C. § 6041(a), every person engaged in a trade or business who makes payments of $600 or more in any taxable year to another person in the course of that trade or business must file an information return. The return must report the aggregate amount of such payments and the name, address, and taxpayer identification number of the payee. In practice, this means a Form 1099-MISC or Form 1099-NEC.21
No individual zucchini transfer approaches the $600 threshold. A single zucchini is worth approximately one dollar. The information reporting requirement therefore does not apply to any individual transfer.
But the absence of information reporting does not create an exclusion from income. The IRS has been explicit on this point: “Even if you don’t receive a Form 1099, the income is still generally taxable.”22 Income that falls below the information reporting threshold is still income. It is simply unreported income. And the IRS has a word for unreported income: the tax gap.
The IRS projected a gross tax gap of $696 billion for tax year 2022, with $539 billion—77 percent—attributable to underreporting on timely filed returns.23 The tax gap represents taxes legally owed but not paid. The IRS acknowledges that the tax gap “cannot fully account for all types of noncompliance.” It does not specify whether the unaccounted noncompliance includes cucurbits. We believe it does.
IX. The Bartering Defense
Some recipients of surplus zucchini reciprocate. A neighbor who receives zucchini in July may leave tomatoes in August or return a loaf of banana bread in September. These reciprocal transfers do not rescue either party from tax liability. They compound it.
Revenue Ruling 79-24 establishes that when two parties exchange property or services, each party must include the fair market value of the property or services received in gross income.24 The exchange of a two-pound zucchini for a loaf of banana bread is a barter transaction. Both the zucchini and the banana bread have fair market value. Both fair market values are includable in both parties’ gross incomes. The transaction does not reduce the tax obligation. It doubles it.
The IRS maintains a Bartering Tax Center page on its website that explains: “Bartering occurs when you exchange goods or services without exchanging money. An example of bartering is a plumber doing repair work for a dentist in exchange for dental services. You must include in gross income in the year of receipt the fair market value of goods and services received from bartering.”25 The IRS does not provide an example involving a zucchini. The omission is conspicuous.
X. The Annual Day of Concerted Noncompliance
August 8 is the single largest coordinated act of federal tax noncompliance in the United States that does not involve a cryptocurrency exchange.
On that date, gardeners across the country execute simultaneous, unregistered, unreported transfers of agricultural property to recipients who have not requested the property, have not provided their taxpayer identification numbers, and in many cases have locked their doors. The transfers are executed at night. The transferors wear dark clothing. The recommended protocol involves “creeping” and “sneaking.”26 These are not the hallmarks of a compliant taxpayer.
The IRS Criminal Investigation Division investigates tax fraud, money laundering, and currency violations. It has 2,116 special agents deployed across 21 field offices.27 On August 8, approximately 13.4 million gardening households are potentially in possession of surplus summer squash. If even 10 percent execute a porch transfer on the designated day, that is 1.34 million unreported transfers in a single 24-hour period. That is 634 unreported transfers per IRS special agent. The enforcement arithmetic is not favorable.
XI. The De Minimis Objection
The anticipated objection is that the amounts involved are too small to matter. A single zucchini is worth one dollar. The IRS does not audit for one dollar.
The response is that the Internal Revenue Code does not contain a de minimis exception for gross income. Section 61(a) says “all income.” It does not say “all income exceeding a threshold that would justify the cost of processing the return.” The Treasury Department has promulgated a de minimis fringe benefit exclusion at 26 U.S.C. § 132(a)(4) and (e), but that provision applies exclusively to employer-provided fringe benefits of such small value that “accounting for it would be unreasonable or administratively impracticable.”28 A neighbor is not an employer. A zucchini is not a fringe benefit. The exclusion does not apply.
And the aggregate is not de minimis. Sixty million dollars of unreported produce transfers annually, at an effective marginal tax rate of 22 percent, represents approximately $13.3 million in foregone federal revenue. That figure does not include state income taxes, which are imposed by 43 states and the District of Columbia on substantially the same income base.
XII. Conclusion
The evidence does not require interpretation. It requires a Schedule C.
Section 61(a) of the Internal Revenue Code defines gross income as all income from whatever source derived. The Supreme Court has held, in Glenshaw Glass, that income includes all undeniable accessions to wealth, clearly realized, and over which the taxpayers have complete dominion. A zucchini is an accession to wealth. A zucchini on a porch has been clearly realized. The recipient has complete dominion over it.
The gift exclusion at § 102(a) requires, under Duberstein, that the transfer proceed from detached and disinterested generosity. The annual holiday designated for the disposal of surplus zucchini is described, by its own creator, as a method of “ridding yourself of unwanted surplus summer squash.” The recommended delivery protocol involves stealth, darkness, and flight. The transferor does not leave a card. The transferor does not leave a taxpayer identification number. The transferor leaves a vegetable and runs.
Approximately 42 million American households grow food. Approximately 13.4 million of them grow summer squash. The University of Maryland Extension documents yields of 20 to 40 pounds per ten-foot row. The IRS has projected a $696 billion gross tax gap for tax year 2022. The agency acknowledges that its estimates “cannot fully account for all types of noncompliance.”
The zucchini is one type.
It is sitting on your porch right now, unreported, its fair market value accruing interest and penalties under 26 U.S.C. § 6651, while the person who put it there retreats into the August darkness with the quiet satisfaction of someone who has successfully externalized both a surplus agricultural product and a federal tax obligation in a single act.
The IRS instructs taxpayers to report all income. It provides forms. It provides instructions. It provides a toll-free number. It does not provide a produce scale.
Ergo.
Sources
- 26 U.S.C. § 61(a), Internal Revenue Code. uscode.house.gov ↑
- Commissioner v. Glenshaw Glass Co., 348 U.S. 426, 431 (1955). law.cornell.edu ↑
- USDA Agricultural Marketing Service, National Retail Report for Fruits and Vegetables. Terminal market prices for summer squash vary by season and region. ams.usda.gov ↑
- 26 U.S.C. § 451 and Treas. Reg. § 1.451-2 (constructive receipt doctrine). ↑
- Rutkin v. United States, 343 U.S. 130, 137 (1952), cited with approval in Glenshaw Glass, 348 U.S. at 431. ↑
- 26 U.S.C. § 102(a). uscode.house.gov ↑
- Commissioner v. Duberstein, 363 U.S. 278 (1960). supreme.justia.com ↑
- Duberstein, 363 U.S. at 285, quoting Commissioner v. LoBue, 351 U.S. 243, 246 (1956) and Robertson v. United States, 343 U.S. 711, 714 (1952). ↑
- Bogardus v. Commissioner, 302 U.S. 34, 41 (1937). ↑
- Duberstein, 363 U.S. at 286. ↑
- Tom Roy, Wellcat Holidays & Herbs, creator of “National Sneak Some Zucchini Onto Your Neighbor’s Porch Day” (August 8). Quoted in Kent State University Trumbull press release and Old Farmer’s Almanac. kent.edu ↑
- Old Farmer’s Almanac, “August 8 is National Sneak Some Zucchini onto Your Neighbor’s Porch Day!” almanac.com ↑
- National Gardening Association Special Report, cited in National Garden Bureau and Forbes: 35% of U.S. households (approximately 42 million) grow food at home. gardenpals.com (citing NGA) ↑
- National Gardening Association: summer squash grown by 32% of food gardeners. Top homegrown vegetables: tomatoes (86%), cucumbers (47%), sweet peppers (46%), beans (39%), carrots (34%), summer squash (32%). thisoldhouse.com (citing NGA) ↑
- University of Maryland Extension, “Growing Summer Squash (Zucchini) in a Home Garden”: “Approximate yield: 20 to 40 lbs. per 10-foot row.” extension.umd.edu ↑
- Zucchini plants produce 3 to 10 pounds per plant over a growing season, with 2 to 3 harvestable fruits per plant per week during peak production. Colorado State University Specialty Crops and multiple university extension sources. agsci.colostate.edu ↑
- University of Missouri Extension, nutrition and health education specialist Dr. Pam Duitsman: “many folks find giving their zucchini to neighbors is a great solution.” morningagclips.com ↑
- Treas. Reg. § 1.61-2(d)(1): “If services are paid for in property, the fair market value of the property taken in payment must be included in income.” ↑
- Rev. Rul. 79-24, 1979-1 C.B. 60. Bartering of services and property results in gross income to both parties. ↑
- Treas. Reg. § 20.2031-1(b): fair market value defined as “the price at which the property would change hands between a willing buyer and a willing seller, neither being under any compulsion to buy or sell and both having reasonable knowledge of relevant facts.” ↑
- 26 U.S.C. § 6041(a): information return requirement for payments of $600 or more. ↑
- IRS, “Understanding Your Form 1099-K”: “Even if you don’t receive a Form 1099, the income is still generally taxable.” irs.gov ↑
- IRS Publication 5869, Tax Gap Projections for Tax Years 2021 and 2022: projected gross tax gap of $696 billion for tax year 2022, with $539 billion (77%) attributable to underreporting. irs.gov ↑
- Rev. Rul. 79-24, op. cit. ↑
- IRS, “Tax Information for Bartering Transactions”: “You must include in gross income in the year of receipt the fair market value of goods and services received from bartering.” irs.gov ↑
- Old Farmer’s Almanac, op. cit.; Dave’s Garden, “National Sneak Some Zucchini Onto Your Neighbor’s Porch Day.” davesgarden.com ↑
- IRS Criminal Investigation, Annual Report: approximately 2,116 special agents. irs.gov ↑
- 26 U.S.C. § 132(a)(4) and (e): de minimis fringe benefit exclusion applies only to employer-provided benefits “the value of which is (after taking into account the frequency with which similar fringes are provided by the employer to the employer’s employees) so small as to make accounting for it unreasonable or administratively impracticable.” ↑